I remember sitting at my kitchen table with $340 in my account, staring at a daycare invoice for $210 and a light bill that was already past due. I did not know yet that a tax credit was waiting for me worth more than that month's whole paycheck. Nobody handed me a list. I found out by accident, from another mom in a Facebook group, two years too late. That is the part that still gets under my skin when I talk to other single moms. The free financial resources for single moms that actually exist, real programs with real money and real help attached, are scattered across a dozen confusing websites and mostly nobody tells you they are there. So here are ten of them. If you already know five, that is still five more dollars in your pocket than you had this morning. Why so many single moms never hear about any of this None of this is because you were not paying attention. Every one of these programs requires you to find it first, prove...
A coworker showed me her cash envelopes once during a lunch break, a small zippered pouch with categories written on index cards inside, and my first honest reaction was that it seemed like something from a decade ago, before contactless payment and direct deposit made carrying actual cash feel almost unnecessary.
I tried it anyway, mostly out of curiosity about whether an old fashioned method could hold up against how differently most of us handle money now. What I found is more nuanced than either dismissing it as outdated or treating it as some universal fix. It works genuinely well for some parts of a budget and poorly for others, and knowing which is which matters more than a blanket verdict either way.
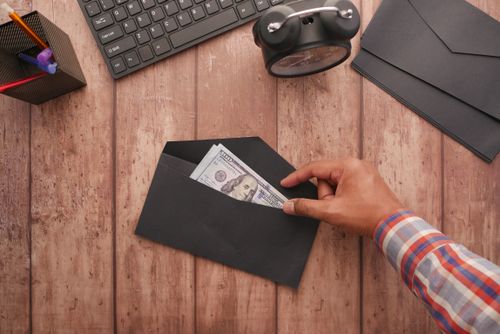
What the cash envelope system actually is
The method is simple. Withdraw cash for specific spending categories, groceries, gas, personal spending, and physically divide it into labeled envelopes. When an envelope is empty, that category is done for the period, whether that's a week or a month, regardless of what's still sitting in your checking account.
The entire mechanism relies on physical scarcity. A checking account balance is abstract, a number on a screen that doesn't visibly shrink the way a stack of bills in an envelope does. Watching an envelope get thinner creates an immediate, tangible signal that a digital balance often doesn't.
Does it actually still work in 2026
Mostly yes, for specific categories, and mostly no as a complete replacement for how most people handle their full budget now.
Cash use has declined significantly over the past decade, and a lot of places, particularly online retailers and increasingly some physical stores, don't accept cash at all anymore. Trying to run every single budget category through cash envelopes in 2026 runs into real friction: online grocery pickup, gas stations that charge a fee for cash inside versus card at the pump, subscription services that only take a card on file.
Where it still works well is the specific categories most prone to overspending precisely because they're currently tracked digitally and therefore invisible in the moment, groceries, dining out, personal spending. These are the categories where the physical limitation of a shrinking envelope provides real friction that a card swipe simply doesn't.
Where it makes sense to start
Pick one or two categories, not your entire budget, the ones that consistently run over month after month despite your best intentions with a digital budget alone. For most people, that's groceries or discretionary personal spending, categories with frequent small purchases that are easy to lose track of individually.
Withdraw the budgeted amount for that category at the start of the week or month, whichever matches how you get paid, and commit to using only that cash for those specific purchases. Bills, gas paid at the pump, anything requiring a card by necessity, stays exactly as it was.
The specific friction that makes this method work
The value isn't really about cash itself. It's about the visible, physical limit that a digital balance doesn't create in the same way.
A checking account showing $340 remaining for the month in a grocery category doesn't feel meaningfully different from $310, even though the second number means less room exists. An envelope with three twenty dollar bills left feels dramatically different from an empty one, in a way that changes the decision at the register in real time rather than after the fact on a statement.
Addressing the practical concerns
Carrying cash raises reasonable safety questions, and the honest answer is that the amounts involved in a specific category envelope, typically $150 to $300 for something like groceries over a month, aren't dramatically different from what most people already carry in a wallet occasionally, though it's worth being mindful about where and how the envelopes are stored.
ATM fees are a real cost if withdrawing cash regularly from a machine outside your own bank's network. Planning the withdrawal around a fee free ATM, either your own bank or a partner network, avoids this becoming an ongoing cost that quietly offsets the benefit of the method itself.
My free Minimalist Budget Planner is where I calculate exactly how much to withdraw for each cash based category before the week or month starts, based on real spending averages rather than a rounded guess that either leaves too much unused or runs out too early.
A specific comparison that shows what changes
A veterinary technician earning $19.40 an hour had run every category of her budget digitally for years, checking her banking app regularly but still finding her personal spending category ran over almost every single month despite genuinely trying to be careful. She started withdrawing $120 in cash every two weeks specifically for that one category, leaving everything else digital.
Six weeks in, she told me the specific moment that changed things wasn't a dramatic realization. It was standing at a register with two twenty dollar bills left in the envelope and a purchase that would have used most of it, and choosing not to buy it, not because of a mental calculation about her digital balance, but because she could physically see there wasn't much left.
Combining cash envelopes with digital tracking
The cash envelope system works best as one specific tool within a broader budget, not a replacement for tracking everything. Bills, savings transfers, and any category that genuinely requires a card stay in your regular digital system, while the one or two categories most prone to overspending get the physical cash treatment.
My Simple Monthly Budget Planner Pro tracks the cash categories alongside everything else digital, so the withdrawal amount for each envelope calculates automatically from your real budget rather than requiring a separate manual calculation every time.
Frequently asked questions
Does the cash envelope system still make sense in 2026 with so many places going cashless?
For specific categories, yes, particularly ones prone to frequent small overspending like groceries or personal spending, where the physical limitation of a shrinking envelope creates real friction a digital balance doesn't. Running an entire budget through cash envelopes is less practical now given how many places, especially online retailers and some physical stores, don't accept cash at all. Most people find the best use of this method is one or two specific categories rather than a full budget overhaul.
How much cash should I withdraw for a cash envelope category?
Base the amount on your real spending average for that category over the past two months, rather than a rounded number that feels reasonable. If your actual grocery spending has been running $340 a month, withdraw close to that amount rather than a lower figure that guarantees running out early or a higher one that defeats the purpose of the physical limit. Adjusting the amount after the first month or two, once you see how the real number holds up, keeps the system accurate.
Is it safe to carry cash for a budgeting system, or is that too risky?
The amounts involved in a typical single category envelope, often $150 to $300 for something like groceries over a month, are generally comparable to what many people already carry occasionally. Being mindful about where the cash is stored, not leaving a full envelope visible in a car or an unlocked bag, addresses most of the practical risk. If carrying a specific amount feels genuinely uncomfortable, starting with a smaller category or a shorter time period, weekly rather than monthly withdrawals, reduces the amount on hand at any one time.
The zippered pouch that changed my mind
That coworker's cash envelopes looked outdated to me at first, and in a lot of ways the method as a complete system is outdated now, given how much of daily spending genuinely requires a card or happens online entirely.
What isn't outdated is the specific friction a physical, shrinking amount creates for the categories most prone to invisible, incremental overspending. Used narrowly, for one or two categories rather than an entire budget, it still works in 2026 exactly the way it worked when it started.
When you're ready to calculate your real cash category amounts and track them alongside your full digital budget, my Simple Monthly Budget Planner Pro handles both together.
Not there yet? Start with my free Minimalist Budget Planner to calculate your first real cash withdrawal amount based on actual spending.
Follow on Instagram and Pinterest for weekly money tips for real incomes.
Would you try cash envelopes for even one category? Tell me which one tends to run over most for you, and I'll tell you honestly whether it's a good fit for this method.
Comments
Post a Comment